
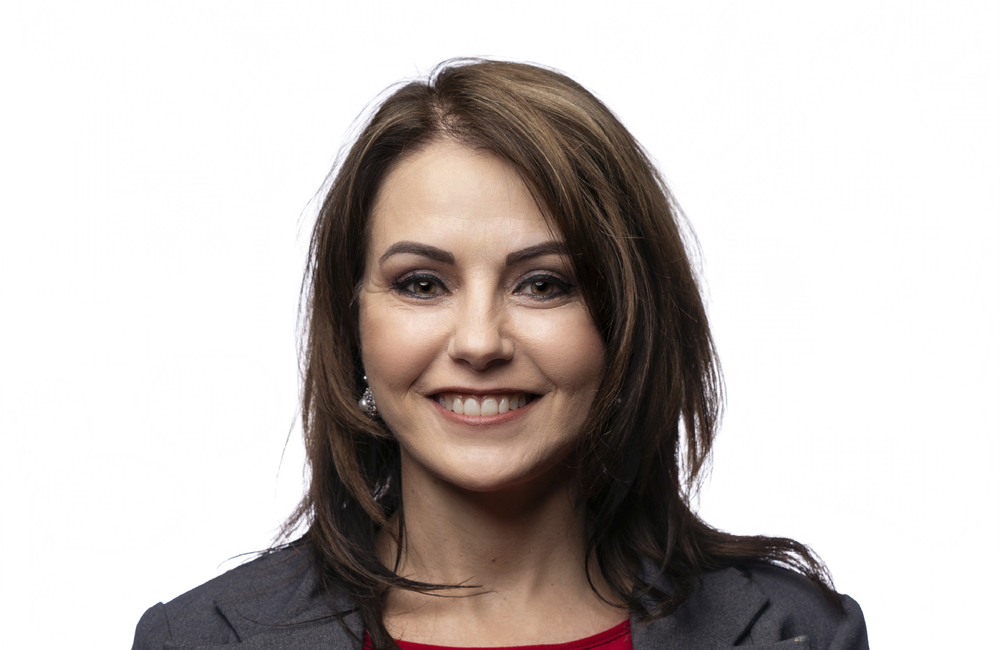
Ralene Grobler | The link between financial stress and mental health
Mental wellbeing and financial wellbeing are usually considered separate issues. But when you are constantly worrying about money, the two are hard to separate.
Many people appear to be doing everything right on the surface. They go to work, look after their families, and keep up with daily life. Privately, however, they’re wondering how they will cover the next bill or cope with an unexpected expense. Financial stress is often a pressure people keep hidden and don’t discuss.
The problem with this is that ongoing concerns about money take up mental space. It can affect how you sleep, how patient you are with the people around you, and how clearly, you think when a decision needs to be made. Relationships can feel the strain too, particularly for families managing rising costs, irregular income, and those supporting extended family.
Stress also changes how we decide. When we are anxious, we focus on whatever feels most urgent right now. All too soon, a familiar cycle takes hold where financial pressure leads to increased worry and uncertainty, which leads to reactive decisions, which leads to further financial pressure.
Borrowing to cover a gap, dipping into long-term savings, or cancelling insurance to free up cash can each feel sensible in the moment, yet make the underlying situation harder to manage.
You may recognise the pattern if you think about money most days, dread opening statements, feel more irritable or withdrawn, avoid money conversations at home, or are unsure exactly what you owe.
When avoidance becomes part of the problem
Avoiding your finances is one of the most human reactions there is. Leaving the envelope or email unopened provides temporary relief. The problem, however, is not temporary. A shapeless worry is often far easier to face once it has numbers attached.
Resolving this problem starts by understanding where you stand:
- List what comes in. Include salary, side income, and any support. If your income varies, use a realistic average rather than your best month.
- List what goes out. Review two to three months of statements, separating essentials from discretionary spending.
- List what you owe. Note each balance, interest rate, and minimum payment.
- Decide what comes first. Housing, essential living costs, and obligations with serious consequences come before everything else.
- You don’t need to fix everything at once. Break it up into small decisions and a handful of specific choices, such as calling a lender or setting up a small automatic transfer to savings.
This is how financial planning interrupts the cycle: it turns a vague sense of dread into a prioritised plan you can work through one step at a time.
Building a resilient financial plan
Resilience means being able to absorb surprises without being knocked off course. A good plan usually looks at things like emergency savings, debt, protection, and longer-term goals.
Even small, regular contributions towards emergency savings help. Ultimately, you want to build up to having the equivalent of several months of essential expenses saved. When it comes to debt, think which balances cost the most, and what you can realistically repay.
Insurance remains an important part of your financial protection, especially when life gets difficult. Rather than cancelling cover, consider reviewing your needs, adjusting your level of cover or exploring ways to reduce premiums, together with the support of a financial adviser.
Longer-term goals include retirement, education, or a home. Break these down into manageable steps. Review your financial plan regularly as your circumstances shift.
Asking for help is not a sign of financial failure. A financial adviser can help you understand your position, set priorities, and build a realistic way forward. They can be an objective sounding board when everything feels emotionally charged.
Bear in mind, however, that financial planning can’t solve mental health challenges and is no substitute for emotional support. If money worries are affecting your sleep, mood, or relationships, speak to your doctor, a counsellor, or a mental-health professional. Dealing with financial stresses, alongside the right support, is part of a broader approach to resilience.
Financial stress doesn’t have to be solved overnight. Sometimes the first step towards feeling more in control is simply understanding where you stand and having a plan for what comes next. Financial wellbeing is not only about having more money. It’s about understanding your financial situation, having a plan, and having the confidence to make decisions when circumstances change.
*Ralene Grobler, Financial Adviser at Momentum Financial Planning.



 Insurance Biz proudly displays the "FAIR" stamp of the Press Council of South Africa, indicating our commitment to adhere to the Code of Ethics for Print and online media which prescribes that our reportage is truthful, accurate and fair. Should you wish to lodge a complaint about our news coverage, please lodge a complaint on the Press Council's website, www.presscouncil.org.za or email the complaint to enquiries@ombudsman.org.za. Contact the Press Council on 011 4843612.
Leave a Comment