
Tackling insurance fraud across Africa requires a collaborative industry effort
Johannesburg - Fraud and abuse are ongoing threats to affordability, customer confidence and the insurance sector’s long-term sustainability.
As the world marks International Fraud Awareness Week (15–21 November), Hollard International is calling for a united and coordinated approach to tackle insurance crime, with greater collaboration between insurers, regulators, law enforcement agencies and other industry stakeholders.
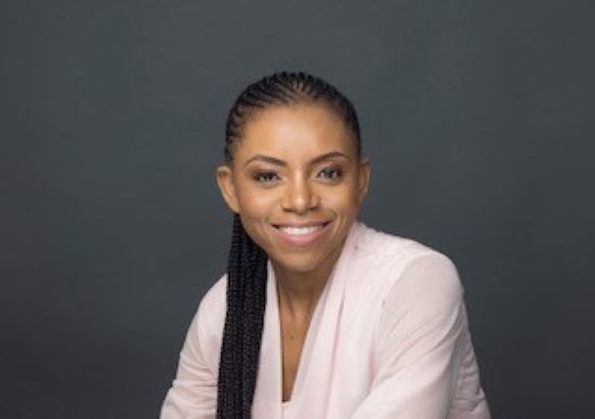
Abbigirl Mahomva, Head of Risk and Compliance at Hollard International, says fraud claims present operational hurdles, requiring more extensive investigations and verification processes, potentially delaying legitimate claims; and it’s customers who need insurance the most who feel the knock-on effects.
Insurance fraud takes many forms, from organised criminal operations targeting vulnerable products and communities to individual attempts to manipulate claims, as well as internal misconduct.
Organised crime and opportunistic fraud
Funeral insurance in the long-term insurance market and hospital or medical gap cover in the general insurance market are among the key areas of concern. These schemes can involve falsified documentation and claims information, sometimes with the cooperation of dishonest healthcare professionals.
Other forms of fraud in the general insurance market involve motor and business insurance, where some customers or brokers may exaggerate accidental damage to secure larger payouts, while some corporate clients facing financial difficulties may falsify claims to obtain much-needed funds.
Internal fraud is another risk, where employees divert payments into fraudulent bank accounts where staff work with organised criminal networks or individuals, exploiting weaknesses in internal systems over an extended period.
Cyber threats are also an emerging risk, with organised criminal activities increasingly taking the form of ransomware attacks, phishing scams and the interception of customer emails.
“While insurance companies generally tend to have processes and controls to scan and manage cyber threats, the weak link is exploitation of third parties processing or holding customer data on behalf of insurers or email interception of customer emails,” says Mahomva.
Digital convenience, new vulnerabilities
According to Hollard International, the expansion of digital and mobile-based insurance has made it easier for customers to access products, purchase cover and submit claims. However, this convenience has also introduced new risks.
Insurance companies rely on multiple technology providers, application developers and cloud-based storage solutions to manage customer information and deliver services. In turn, this creates more problems in a digital environment where information is exposed through vulnerabilities outside an insurer’s direct control.
“Going digital has opened new vulnerabilities,” says Mahomva. “While digital and mobile-based insurance products improve access and make it easier to purchase insurance and submit claims, it has created multiple points through which fraudsters can exploit customers, intercept information and gain access to customer databases.”
She adds that customers have limited visibility of how their information moves between digital platforms, service providers and insurers. This makes it important for insurers to extend risk management beyond internal platforms and to ensure that third-party providers meet appropriate security standards.
The cost to customers and the industry
As fraudulent payments increase claims costs, insurers face additional operational expenses from suspicious activity and strengthening controls and these costs can raise premiums.
“It increases the number of checks that need to be done before settlement of a claim, which may delay the claims turnaround time and inconvenience customers at a time when those funds are desperately needed,” says Mahomva.
This can undermine confidence in the industry, with customers potentially choosing to cancel or avoid insurance altogether.
Mahomva notes that prevention, responsible product design and customer education are essential for funeral insurance. In addition, insurers have a responsibility to help communities understand their funeral cover while introducing appropriate safeguards to protect against exploitation.
These could include disclosure and consent from individuals added to funeral policies to establish their insurable interest.
Furthermore, sales practices require a deeper look, as commission structures based solely on sales volumes can encourage unethical behaviour, including fraudulent sales and aggressive selling.
“My view is that insurers have a bigger role to play in driving shared value by offering products that customers can afford and where the remuneration structures do not create an unethical culture of fraudulent sales,” she says.
Prevention must become an industry priority
Addressing insurance fraud demands more than individual insurers strengthening their internal controls.
South Africa provides an example through the South Africa Insurance Crime Bureau (SAICB), which brings together insurers, law enforcement agencies and other stakeholders to address insurance-related crime.
Continent-wise, the African Insurance and Banking Anti-Fraud Professionals Consortium (AIBFPC) is a network of professionals across the insurance and banking sectors working together to combat fraud.
“The biggest challenge with tackling fraud often relates to the law enforcement aspects, litigation and prosecution, where investigations, court proceedings and bringing criminals to book are an administratively long process,” says Mahomva. She notes that corruption and bribery can complicate efforts; with some cases remaining unsolved indefinitely.
The industry needs to implement stronger internal controls, better use of data and technology, responsible product development, customer education and effective regulatory oversight.
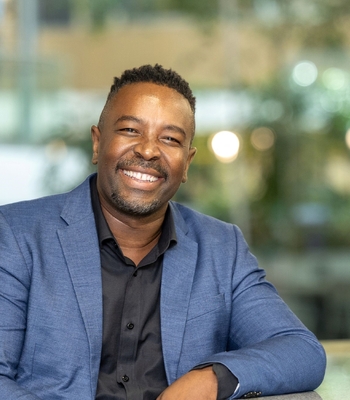
Pravin Kalpagé (PK), CEO of Hollard International says, “Insurance fraud is an industry-wide concern that affects the affordability of insurance and ultimately threatens the sustainability of the sector.
“As insurers, we have a collective responsibility to tackle fraud decisively, not only to protect our businesses, but also to protect honest policyholders who rely on us when they need us most. To achieve this, we need stronger industry collaboration, responsible business practices and a shared commitment to combating fraud. This remains essential to building a more trusted, resilient and sustainable insurance industry across Africa.”




 Insurance Biz proudly displays the "FAIR" stamp of the Press Council of South Africa, indicating our commitment to adhere to the Code of Ethics for Print and online media which prescribes that our reportage is truthful, accurate and fair. Should you wish to lodge a complaint about our news coverage, please lodge a complaint on the Press Council's website, www.presscouncil.org.za or email the complaint to enquiries@ombudsman.org.za. Contact the Press Council on 011 4843612.
Leave a Comment