
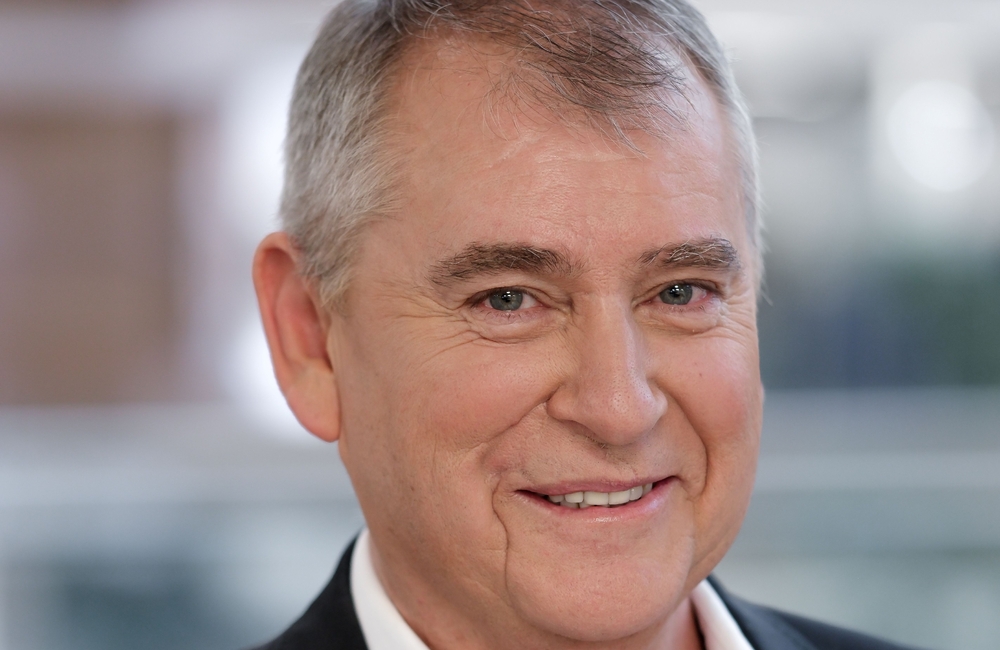
George Kolbe | Are you protected for the risks people are actually claiming for today?
Spring is traditionally a season for resetting, decluttering, and shaking off the old to make way for the new. While we regularly clean out our homes, clear out our cupboards, and review our monthly budgets, there is another area that can quietly become outdated: our financial protection.
For many South Africans, taking out life insurance is usually accompanied by a significant milestone such as buying a home, getting married, or welcoming a first child. Once that policy document is signed and filed away, however, most people tend to forget all about it.
That can be costly because life doesn’t stay static. Over time, income levels change, families grow, career trajectories shift, and financial commitments evolve. Continuing with a policy arranged years ago without checking whether it still matches your current reality can leave large gaps in your financial safety net.
Momentum Life Insurance’s 2025 claims statistics suggest that the protection conversation is changing too. In 2025, critical illness claims exceeded R1 billion, increasing by more than 15% year on year, while 45% of income protection claims were permanent disability cases.
This spring, rather than simply checking whether you have life cover, it may be worth asking a more important question: does your protection still reflect the risks you and your family face today?
When your life changes, your cover should too
There is a common assumption that once life cover is secured, the protection conversation is finished. In reality, financial protection needs evolve alongside your circumstances. Life cover forms an important foundation, but broader life insurance protection can also help protect against risks such as critical illness, disability, or the loss of income.
Consider how your life may have changed since you first put your policy in place. Has your income grown? If so, does your current cover adequately replace your lifestyle and earning potential for your family if you are no longer there? Have you taken on a larger home loan, financed a business, or accumulated new financial obligations? Conversely, have older debts been settled?
Have you welcomed another child, or are your children now financially independent? Have you taken on financial responsibility for ageing parents? Have major life events, such as marriage, divorce, or a new birth, taken place since you last updated your beneficiary nominations?
These are all reasons to revisit your protection and ask whether it still reflects your current circumstances, not just in terms of how much cover you have, but what you are actually protected against
Don’t forget your beneficiaries
Reviewing your cover is not only about ensuring you have the right level of protection. It’s also about making sure your beneficiary nominations still reflect your wishes and family circumstances.
Marriage, divorce, the birth of a child or other significant life events can all be reasons to revisit who is named as beneficiaries on your policy. If beneficiary nominations are outdated, your policy may no longer reflect who you would want to receive the benefit.
Simple prompts for your spring review
To determine whether your life insurance policy needs a refresh, consider these questions:
- Has my income changed? Does my current protection still reflect the income my household relies on?
- Have my financial commitments changed? Are my current debts, including home loans or vehicle finance, adequately covered?
- Has my family situation changed? Are my beneficiary nominations still up to date?
- Am I protected against more than death? Do I have protection for serious illness or disability that could affect my ability to earn an income and provide for my family’s needs?
Proactive protection builds financial confidence
Reviewing your cover should never be driven by fear or anxiety about what could go wrong. Instead, it should form part of a proactive approach to financial wellbeing. Knowing that your protection accurately reflects your current income, commitments, and family circumstances provides peace of mind that your loved ones and financial goals remain protected.
This spring, take time to check in on your protection. As your life evolves, keeping your life cover and broader life insurance protection aligned with your journey can help ensure that what matters most remains protected.
*George Kolbe is Head of Life Insurance Marketing and Enablement at Momentum Life Insurance.




 Insurance Biz proudly displays the "FAIR" stamp of the Press Council of South Africa, indicating our commitment to adhere to the Code of Ethics for Print and online media which prescribes that our reportage is truthful, accurate and fair. Should you wish to lodge a complaint about our news coverage, please lodge a complaint on the Press Council's website, www.presscouncil.org.za or email the complaint to enquiries@ombudsman.org.za. Contact the Press Council on 011 4843612.
Leave a Comment